Call Monday-Friday 9am - 5pm Closed Weekends & Bank Holidays

[ Contact Us ]
Need Help? Calling from a mobile please call 0151 647 7556
0800 195 4926Do you have a question? or need help?
Call Monday-Friday 9am - 5pm Closed Weekends & Bank Holidays,
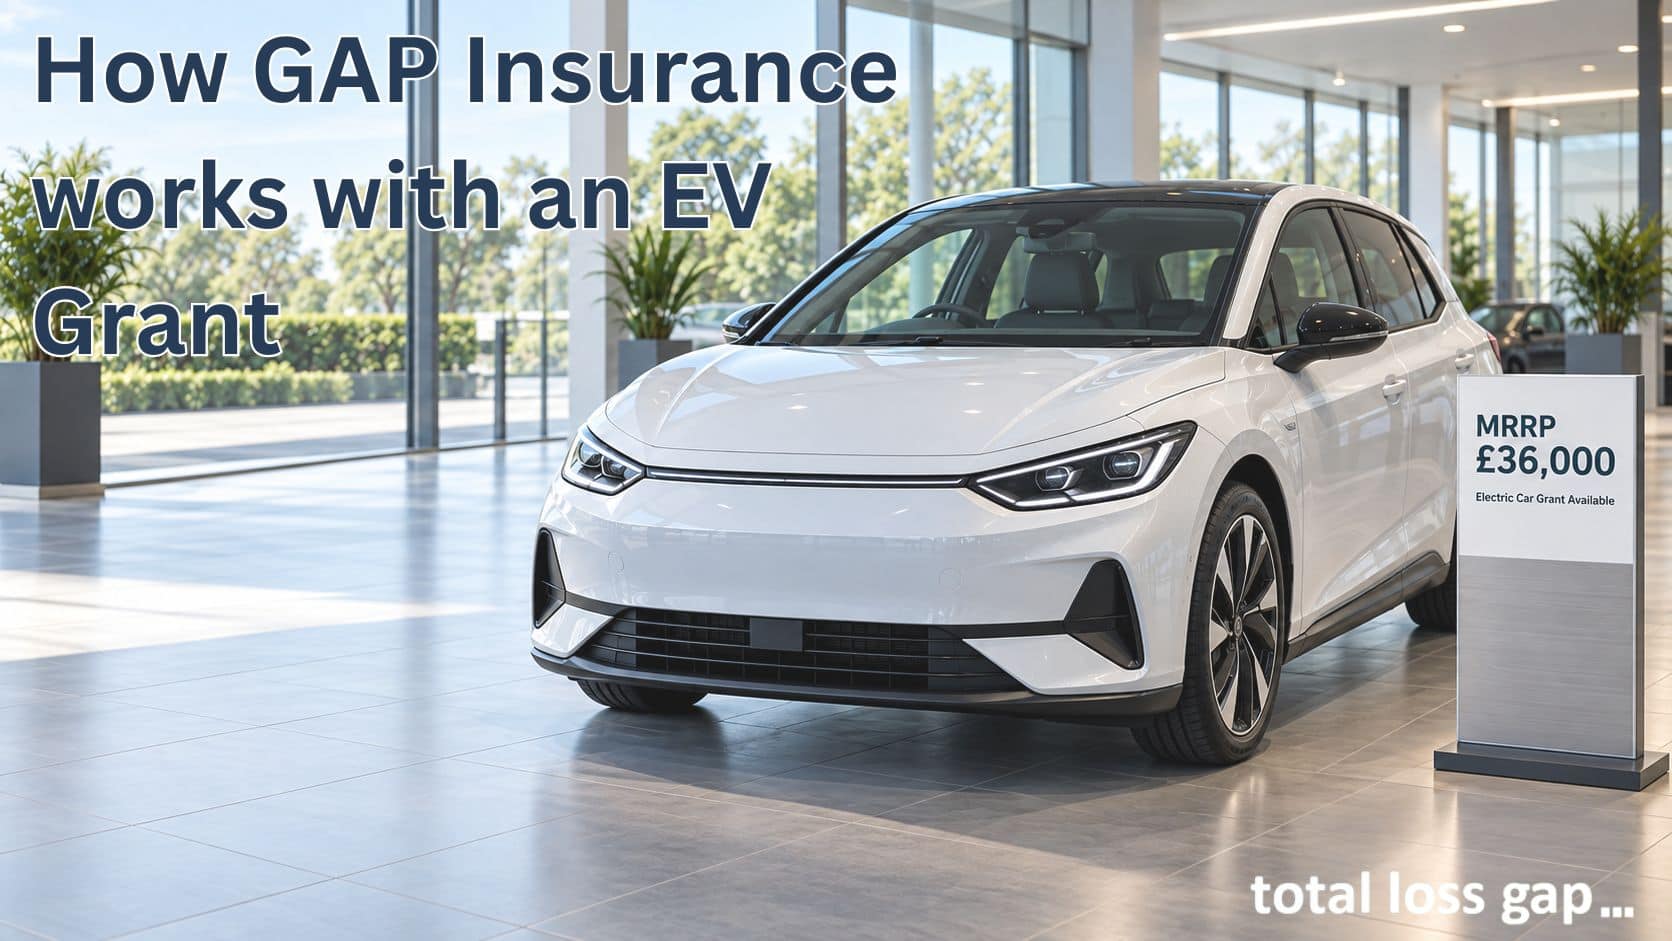
Electric cars are getting more popular, and the government is helping to bring the price down. The Electric Car Grant was introduced in July 2025 and runs until March 2030. It takes up to £3,750 off a qualifying new electric car.
That helps when you buy. It can also reduce what a GAP policy pays if the car is written off. How much it matters depends on how the policy measures the price you paid.
Our two current GAP Insurance products handle the grant differently.
Combined Return to Invoice pays against the net price you paid, so the grant lowers the payout. Combined Invoice and Replacement GAP can instead cover the cost of a replacement car, measured net of any grant you would receive on that replacement. The grant still matters, but what it does depends on what replacement prices do.
You don’t claim the grant yourself. The dealer or manufacturer applies it, and it comes off the price when you buy. The invoice should show the vehicle price, the grant and the final amount.
Grant amounts, eligible models and price limits change, so check GOV.UK before you buy.
Say the car lists at £36,000 before the grant. After a £3,750 grant, you pay £32,250.
Combined Return to Invoice pays the gap between the motor insurer’s settlement and the higher of two figures: what you still owe on finance, or your net invoice selling price.
The policy defines net invoice selling price as the purchase price, including factory-fitted options and up to £1,500 of manufacturer-endorsed dealer-fitted accessories, after any discount. A grant taken off the invoice counts as a discount, so it lowers that figure.
Take the £32,250 price above. If the motor insurer settles at £22,000 after a write-off, the GAP payment is £10,250 (illustrative). Together, the two payments come to £32,250, the amount you actually paid. The grant isn’t added back, because you never paid that part.
That’s a fair result, but it means a buyer who gets the grant has a lower invoice figure, and so lower cover, even though the car cost them less.
Combined Invoice and Replacement GAP pays the gap between the motor settlement and the highest of three figures: what you owe on finance, your original net invoice selling price, or the cost of a replacement vehicle. The replacement can be the same specification or an equivalent superseding model if the original has been discontinued.
Because the invoice price is one of those figures, this policy won’t pay less than Return to Invoice on the original car. It pays more only when the replacement cost is higher.
The replacement cost is set at the date of loss, for a car of the same age, model, specification and mileage as yours was when you bought it. For a new car, we average three franchised dealer offers, which may include online quotes. For a used car, we use Glass’s Guide retail values alongside vehicles available in the UK retail network.
Replacement cover puts you back where you were. It doesn’t put you in a better position than before the loss. So if you would receive a government grant on the replacement, its cost is measured net of that grant. If you wouldn’t, because the model has left the scheme or you don’t qualify, the grant doesn’t reduce it.
The policy doesn’t spell out how a grant on the replacement model is treated. Ask the administrator to confirm this in writing before you buy.
The grant is still available. The original car was bought for £36,000 before the grant, leaving a net invoice price of £32,250. After a £22,000 settlement, Return to Invoice pays £10,250. A replacement EV now lists at £39,000 before the grant, and a £3,750 grant still applies, so its net cost is £35,250. Combined Invoice and Replacement GAP pays £13,250 (illustrative). The gross figure of £39,000 would give £17,000, but that would leave you £3,750 better off than before the loss, which insurance doesn’t allow.
The grant has gone. Suppose the replacement model no longer qualifies. There’s no grant to deduct, so the replacement cost is the full £39,000. Return to Invoice still pays £10,250. Combined Invoice and Replacement GAP pays £17,000, which is £6,750 more. This is the situation the replacement product is built for.
Replacement prices fall. If the net replacement cost drops to £30,000, that’s below your £32,250 invoice price. The policy uses the higher figure, so it pays £10,250, the same as Return to Invoice. Replacement cover can’t pay less, but it doesn’t always pay more.
Replacement cover makes most sense when the existing car had a large grant, the model could leave the scheme or drop a grant band, the model might be replaced by something dearer, or you expect EV prices to rise during your cover.
It adds less if the grant was small, the model is stable or prices are falling. Replacement cover costs more, so price both products on the same car before you choose.
Both products generally need buying within 180 days of taking ownership of the car. That stretches to 365 days for a new car where your motor insurer gives new-for-old replacement in the first year.
Return to Invoice GAP is available for cars under 10 years old with under 100,000 miles at the start of cover.
Invoice and Replacement GAP is narrower, covering cars under four years old with under 40,000 miles. Both need the car to be listed in Glass’s Guide and to have a net invoice price between £5,000 and £100,000.
Combined Invoice and Replacement GAP has a maximum benefit of £75,000 for cars priced between £75,000 and £100,000.
Notify us within 120 days of the date of loss. Don’t accept the motor insurer’s settlement offer until the administrator has authorised it. If you accept first, your claim may be settled on the car’s market value at the date of loss, and the administrator can’t try to negotiate a higher figure for you.
Keep your purchase invoice, because it shows the grant and the final price.