Land Rover Theft Gang Jailed - A case for GAP Insurance?
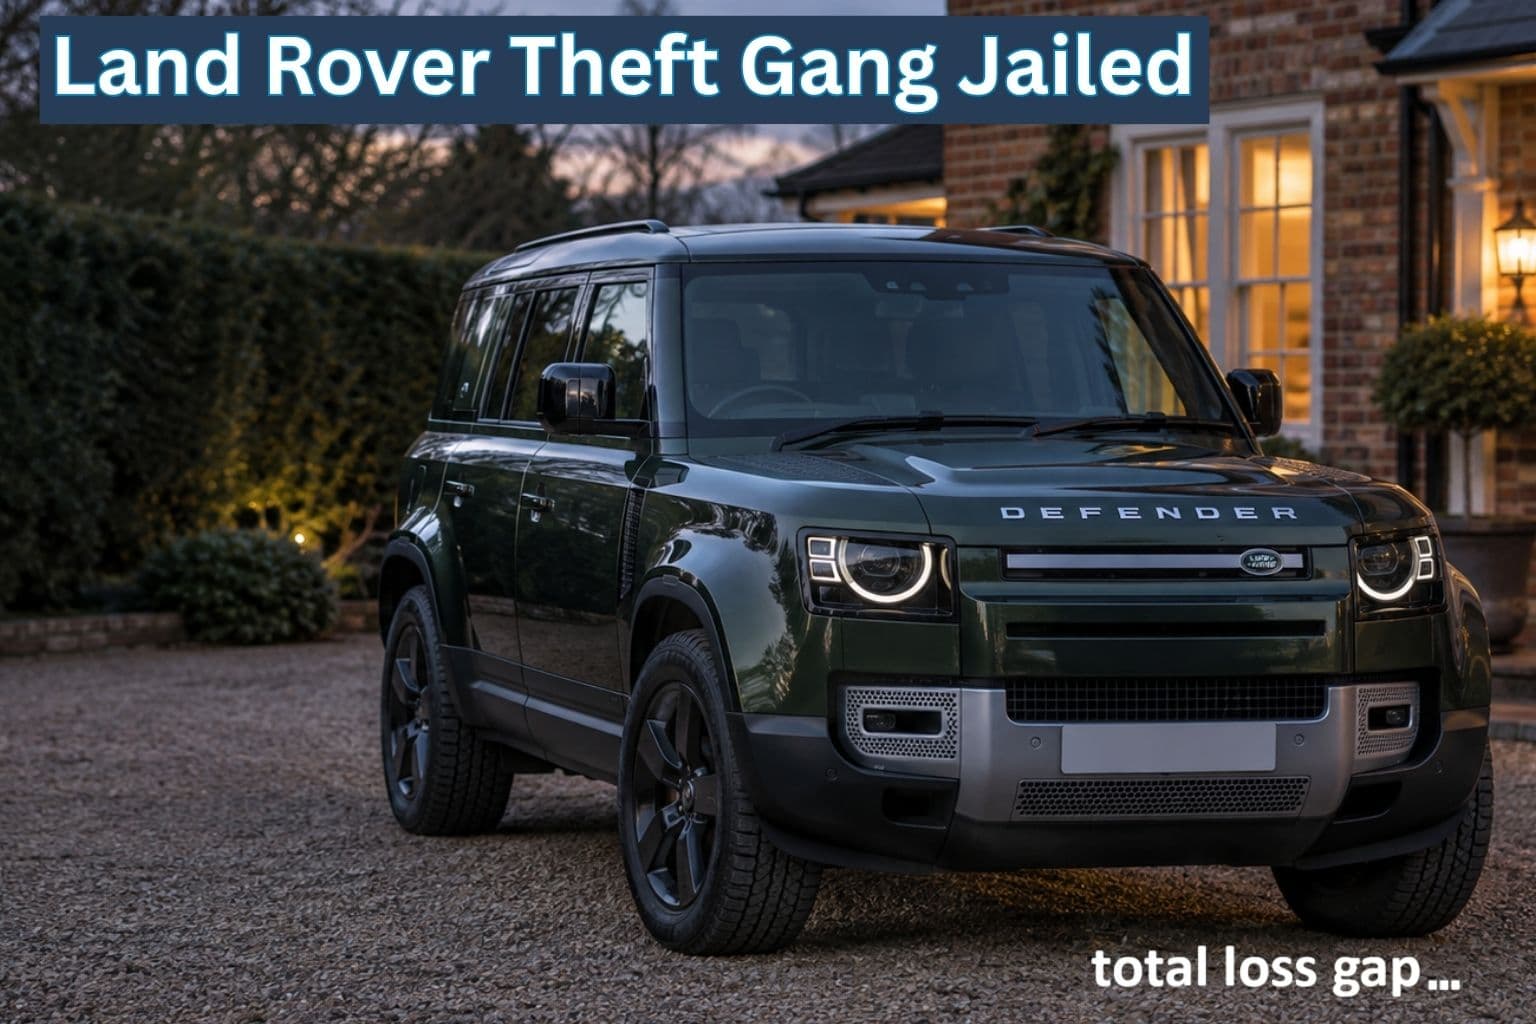
Four men have been jailed for stealing 33 Land Rover Defenders and have received combined prison sentences of fifteen years and nine months.
The courts confirmed the sentences on 18 September 2026, following thefts across six police force areas.
West Mercia Police
For vehicle owners, the story raises a practical question: if your car is stolen, how much of the money you have invested in it would your insurance actually return?
The answer depends on your motor policy, any outstanding finance and whether you have additional protection for an eligible financial shortfall.
What happened in the Land Rover theft case?
The case involved 34 stolen vehicles, including 33 Land Rover Defenders, which police said were worth more than £600,000.
The spree took place between September 2024 and May 2025.
Police said a Bristol workshop was used as a chop shop, where stolen vehicles were taken, and parts were subsequently found. CCTV evidence, automatic number plate recognition and mobile phone evidence helped connect the offenders to the thefts.
West Mercia Police
This is a newly reported sentencing outcome for earlier offences. It does not, by itself, establish a current increase in Land Rover theft or show the likelihood of an individual owner’s vehicle being stolen.
What will your motor insurer pay if your car is stolen?
If a stolen vehicle is not recovered and the insurer accepts the claim as a total loss, the settlement will usually be based on its market value immediately before the theft.
A fair market-value payment can therefore still leave a difference between what you receive and what you originally paid.
For illustration, suppose you bought a vehicle for £50,000 and its accepted market-value settlement at the time of theft is £38,000. The difference from your original purchase price is £12,000. These are hypothetical figures, before considering an excess, finance or the terms of any GAP policy.
What if the vehicle is on finance?
The relevant comparison may also include the amount required to settle your finance agreement. Total Loss GAP’s claims guide explains that finance protection can consider an outstanding finance balance, while lease and contract hire cover uses the relevant lease settlement. The calculation depends on
your policy.
How GAP Insurance claims are calculated
Using the illustration above, if the finance settlement were £41,000 and the motor insurer paid £38,000 towards it, the difference would be £3,000. That is a different figure from the £12,000 difference against the purchase price.
This is why “covering the finance” and “getting back what you paid” should not be treated as interchangeable goals.
Where can GAP Insurance help?
GAP Insurance can cover an eligible shortfall following a total loss. Different types use different reference points: the original invoice price, an eligible finance settlement or the cost of an equivalent replacement vehicle. Limits, exclusions and the policy’s calculation rules still apply. It does not simply replace a theft claim that your motor insurer has declined.
Total Loss GAP’s claims calculation guide
Our Combined Invoice and Replacement GAP cover compares the motor insurer’s settlement with the highest applicable figure from the original purchase price, eligible outstanding finance and equivalent replacement cost, subject to the policy terms.
For replacement cover, we compare it to the vehicle’s age, mileage, and specification
when you bought it. For example, a vehicle bought new is assessed against an equivalent new replacement; a vehicle bought used is assessed against the corresponding used equivalent.
Total Loss GAP: Vehicle Replacement cover
A real theft claim: why replacement cost can matter
A separate claim published by Total Loss GAP illustrates the difference between purchase price, market value and replacement cost.
A customer bought an ex-demonstrator Toyota Land Cruiser for £39,500 in November 2020. After it was stolen in May 2025, the motor insurer settled at £32,500. The customer’s five-year Combined Invoice and Replacement GAP policy paid a further £35,945, taking the combined settlements to £68,445. The published case explains that equivalent replacement costs had increased substantially during ownership.
Read the full Total Loss GAP claim example
This Toyota claim is unrelated to the Land Rover prosecution. It is an individual example, not a typical payout or a guarantee of what another policyholder would receive.
What should you do if your vehicle is stolen?
Report the theft to the police and your motor insurer straight away. GOV.UK advises having the registration number, make, model and colour available. The police will provide a crime reference number, which you will need for your insurance claim.
GOV.UK: reporting a stolen vehicle
If you have a Total Loss GAP policy, contact the claims team before accepting your motor insurer’s settlement offer. Our claims guidance explains that the team may need your purchase invoice, finance settlement letter, motor insurer’s settlement letter and crime reference number. A vehicle recovered, repaired and returned to you does not trigger a GAP claim under that guidance.
How to make a Total Loss GAP claim
If you believe the motor valuation is not right, ask the insurer to explain how they arrived at that figure, with supporting evidence.
Check which financial figure your cover protects
Before choosing cover, establish whether your priority is an outstanding finance balance, the price you paid or the cost of an equivalent replacement. Also check whether your motor policy already provides new-vehicle replacement and the conditions attached to it.