10 reasons why a cosmetic repair claim may be turned down
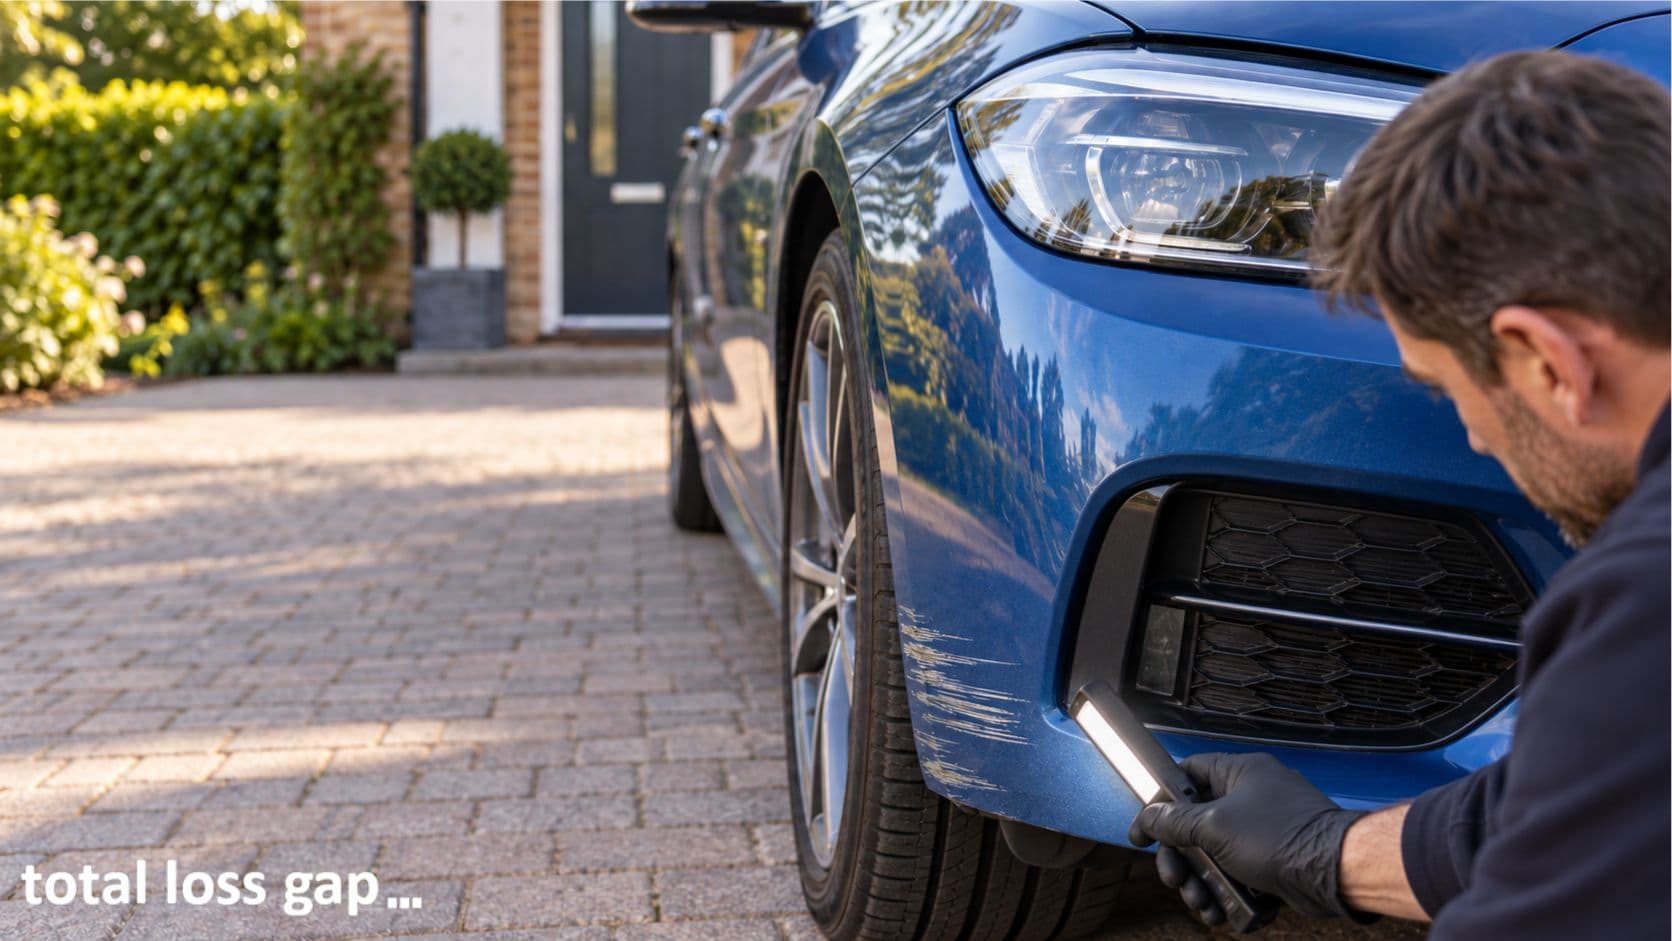
A scratched door, scuffed bumper or kerbed alloy wheel can be frustrating, and often more expensive to put right than it first appears. Claiming on your main motor insurance may make little financial sense once you factor in your compulsory and voluntary excess.
At Total Loss GAP, we are on course to sell twice as many cosmetic repair insurance and maintenance products in 2026 as we did in 2025.
The appeal is understandable. Drivers want to keep their vehicles looking good, protect their part-exchange value and reduce the risk of damage charges when returning a lease or PCP vehicle. Our own
SMARTCare cover is designed with exactly this in mind.
Specialist products can help with eligible repair costs. However, they have limits, and damage that looks minor is not always suitable for the type of repair provided.
Here are ten reasons why a cosmetic repair claim may be turned down, and what to check before buying or requesting a repair.
A note on the products discussed: cosmetic repair insurance and maintenance plans are different products. Their benefits, exclusions and procedures vary. This guide explains issues to look out for; the terms supplied with your particular policy or plan determine what is covered.
1. The damage was already there before cover began
Cosmetic repair cover is generally intended for eligible damage that happens during the period of cover. Existing scratches, dents or wheel damage are normally excluded.
Buying a policy today, for example, would not normally let you claim for a bumper scuff that happened last month.
Some products also require photographs or a vehicle condition assessment before cover can operate. Complete these requirements promptly and make sure the photographs clearly show the vehicle's condition.
If your vehicle already has damage, ask how this affects eligibility before buying.
2. The damage is too extensive for a SMART repair
Cosmetic repair products commonly rely on SMART repair techniques: methods designed to repair a relatively small, localised area.
The terms may limit the length, diameter or depth of damage, as well as the number of panels affected.
A short scratch on one door and a scratch running along the entire side of the vehicle may look like the same type of problem, but they can require very different work.
The nominated repairer also needs to assess whether a suitable result can be achieved using the approved techniques. Damage can fall within the stated measurements and still be unsuitable for the repair process.
Check both the size limits and the repair requirements. Meeting one does not guarantee that the damage qualifies.
3. The damaged component or bodywork area is excluded
Cosmetic repair cover does not necessarily extend to every visible part of a vehicle.
Glass, lights, trims and other components may fall outside its scope. A broken mirror glass, for example, is a different repair from a scratch on a painted mirror housing.
Particular bodywork areas can also carry restrictions. Total Loss GAP's SMARTCare wording, for example, limits repairs on horizontal surfaces, such as roofs, bonnets and boot tops, to eligible stone chips.
The location of the damage can therefore matter just as much as its size.
4. A panel or bumper is cracked, split or needs replacing
A scuffed bumper and a cracked bumper can both result from a low-speed parking incident, but they are different repair jobs.
A scuff may suit a localised cosmetic repair. A crack, split or hole can require work beyond the product's scope, while a damaged panel or bumper may need replacing.
Cosmetic repair products are generally designed to repair eligible surface damage. Replacement body parts are normally outside that scope.
This explains why a small crack can be excluded even when a larger, more noticeable scuff might qualify. The nature of the damage matters as well as its appearance.
5. The alloy wheels or their finish are excluded
Where alloy wheel repairs are included, check which wheels and finishes qualify.
Some products restrict cover to original manufacturer wheels. Aftermarket wheels, chrome finishes, split rims and other specialist designs may be excluded.
A wheel might be repairable by a specialist but still fall outside the product's terms or approved repair process.
If you have changed your wheels or had them refinished, mention this when checking eligibility. Photographs may help the provider identify the finish.
Do not assume every alloy wheel qualifies simply because the product includes alloy wheel protection.
6. The vehicle has an excluded paint finish or body wrap
Matt paint, bespoke paintwork and vehicle wraps can require different treatment from a conventional painted surface.
A product may exclude these finishes because restoring the affected area falls outside its approved repair methods.
Non-standard paint is not necessarily impossible to match. The question is whether the product covers that finish and whether its repairer can carry out the permitted work.
Check before buying cover if your vehicle has a specialist finish. Some paint finishes can't be repaired with SMART techniques.
If you later arrange a respray or wrap, ask the provider how this affects your existing protection.
7. The problem is wear or deterioration rather than covered damage
A vehicle's appearance can deteriorate without a specific accident.
Fading paint, corrosion, peeling finishes, and defects from an earlier poor repair can all look unsightly. However, they are not necessarily covered in the same way as a fresh scratch or scuff.
Total Loss GAP's SMARTCare cover summary, for example, lists wear and tear, corrosion, rust, fading and neglect among its exclusions (
read the cover summary).
When reporting a problem, explain accurately what happened and when you first noticed it. Not every cosmetic defect qualifies for a repair.
8. The relevant claim limit has been reached
Products can limit both the amount available for repairs and the number of claims or repair requests permitted.
You may have used your annual allowance, reached an overall limit or requested work costing more than the applicable financial limit.
Different products have different limits. For example, our SMARTCare Cosmetic Insurance allows up to 5 claims per year of cover, and claims cannot be carried over. We also offer a Cosmetic and Alloy Wheel Maintenance Plan that allows up to 10 alloy wheel repairs and up to £3,000 aggregate for cosmetic bodywork claims over the entire period of the plan.
Check how separate areas of damage are counted, too. One incident or one repairer visit does not necessarily equal one claim.
Ask the claims team before assuming you can simply pay the difference on a repair that exceeds a limit or otherwise falls outside the product's scope.
9. The damage was reported too late
It can be tempting to leave a small scratch until the vehicle is due to go back, then deal with all the repairs together.
However, your product may require damage to be reported within a specified period after the incident. Waiting until the end of a lease or PCP agreement could put you outside that timeframe.
For example, Total Loss GAP's January 2026 SMARTCare product requires damage to be reported within
30 days of the incident.
Other products may have different requirements.
Report damage promptly and within the deadline stated in your terms, even if you would prefer the repair to take place later.
10. Repairs were arranged without prior approval
Do not assume you can book a repair yourself and claim the cost back afterwards.
Your provider may need photographs to assess the damage, confirm eligibility and authorise the work through its approved repair network.
Arranging your own repair before receiving approval can mean the cost is not reimbursed, even if the original damage might otherwise have qualified.
Contact the claims team first. If a workshop repair or a different repairer is proposed, obtain any required authorisation before work begins and keep a record of it.
What if there is nowhere suitable for a mobile repair?
A mobile repairer needs somewhere safe and practical to work. A roadside parking space, driveway or car park will not automatically be suitable for every repair.
If your location is unsuitable, speak to the claims team about the available arrangements. An appointment that cannot proceed at one location does not necessarily mean the underlying claim has been declined.
It is worth checking the location requirements before buying, particularly if you rely on street parking.
How to avoid surprises when you claim
Before buying, check that the product suits your vehicle, its paint finish and its wheels. Read the repair limits, exclusions and any requirements for photographs or a condition assessment.
If damage occurs, report it promptly, provide clear photographs and wait for approval before arranging work.
If a claim is turned down, ask for a clear explanation and the specific policy or plan term behind the decision. If you believe relevant information has been overlooked, ask for the decision to be reviewed.
Cosmetic repair products can help with the cost of eligible minor damage. Understanding the repair limits and exclusions before you buy makes it easier to choose the right protection, and to know what to expect if you ever need to use it.
To explore the cover available from Total Loss GAP, visit our
SMARTCare cosmetic insurance page, where you can review the benefits, exclusions and policy documents before getting a quote.
Sources and further reading